
For most buy-to-let investors in Israel, the practical sweet spot is a 3 or 4-room apartment with a secure room (Mamad) in a neighborhood with proven rental demand. Smaller units cost less to enter and can show a higher percentage yield. Larger units attract longer-staying tenants and a wider pool of buyers when you sell. The right answer still depends on your budget, your exit plan and, above all, the specific location, so this guide walks through how to decide.
If you are used to talking in square feet or square meters, the first adjustment is the room count. An Israeli listing says “4 rooms”, meaning three bedrooms-type rooms plus a living room, or other combinations, and the number is the shorthand everyone uses to search, price and compare. Two “4-room” apartments can differ by 20 square meters or more, so the room count tells you the category, and the built area, the layout and the balcony tell you the real value.
For an investor this has two consequences:
Also check what the listing counts. A “gross” figure includes walls, shared stairwell shares and sometimes a storage room, while the “built” or registered figure is what the Land Registry shows. Ask for both and compare it with the building permit.
There is no universally best size. Each size solves a different investor problem.
| Size | Entry cost | Typical tenant | Strengths | Watch out for |
|---|---|---|---|---|
| 2 rooms | Lowest | Singles, couples, students, young professionals | Low ticket, strong percentage yield potential | Faster turnover, thinnest resale pool, can be cramped |
| 3 rooms | Low to mid | Couples, small families, young professionals | Broad rental demand, easier to finance | Competes with many similar units |
| 4 rooms | Mid | Families | Stable, longer tenancies, widest resale audience | Higher ticket, slightly lower percentage yield |
| 5 rooms and larger | High | Larger families, relocating professionals | Strong appeal for owner-occupiers at exit | Smaller tenant pool, bigger vacancy risk, the lowest liquidity |
This is a framework built on how the market generally behaves, not a promise for any one building. Local data on your street can overturn it.
Small units are attractive when your capital is limited or when you want to spread money across more than one asset. Per shekel invested, rent on a smaller apartment is often a bigger share of the price, which is why small units appear to win on yield. Two things erode that advantage.
First, turnover. Tenants in smaller units tend to stay for shorter periods, and every gap between tenants costs rent, cleaning, repainting and a broker or advertising effort. Tenants of small apartments also often move with very little furniture, which makes relocating easy for them (for a sense of how light a small move can be, see this Dutch-language guide to planning a small move). That is good for tenant mobility and not so good for your vacancy rate.
Second, exit. Buyers who live in the apartment usually want a family-sized home, so the pool of eventual buyers for a very small unit is mostly other investors. In a market where investors are the group that has pulled back, that matters, as discussed below.
A 4-room apartment fits the largest group of tenants who commit for years: families. They put children in local schools, join the community and prefer not to move. For a religious family, proximity to a synagogue, school and community institutions often fixes the choice of neighborhood before the choice of apartment, which makes a well-located 4-room unit one of the easiest rentals to place. It is also the category with the deepest pool of owner-occupier buyers when you decide to sell.
The trade-off is a higher purchase price and a yield that is usually a bit lower in percentage terms than a smaller unit in the same building. You are paying for stability and liquidity.
Larger apartments, garden units and penthouses can appreciate well in desirable areas, and they are what many owner-occupiers aspire to. As rentals they depend on a thinner group of tenants who can afford a high monthly rent. If you buy big, do it because you believe in the location and the exit, not because you expect effortless rental income. Our luxury property insights go deeper on that segment.
In Israel, a residential secure room (Mamad) is built into modern apartments and is a standard part of what tenants ask about. The Bank of Israel studied how much extra it adds. The central finding: the Mamad premium in asking rents rose significantly compared with the period before the war, with most of the rise starting in May 2024. On purchase prices, the picture is calmer. Based on actual transactions, apartments with a Mamad were about 8.2% more expensive than comparable ones without one just before the war, and that premium fell to about 6.4% during the war period covered by the study.
What this means when you choose a size:
In short: when two apartments are close in size, take the one with a proper Mamad, and negotiate on the basis of realized transaction premiums, not on asking prices.
Size decisions sit inside a market cycle, and the cycle has shifted.
According to the Bank of Israel Annual Report 2025, national home prices fell 0.9% year on year in 2025, and transactions fell by about 11% compared with 2024, with the drop concentrated among first-time buyers and investors. Around 91,000 transactions were recorded. The same report notes that the stock of unsold new homes rose through the year to a high level relative to history, because construction starts were strong while sales were weak. The Bank’s chapter on the housing market puts 2025 housing starts at about 80,000 units.
The supply side is also growing. The CBS reports that Israel had about 3.02 million dwellings as of July 2025, 1.9% more than a year earlier, with Jerusalem holding the most units (251,885). The same release says planning authorities approved 223,000 new units in 2025.
For your size decision, the practical implications are:
For a wider view of how to read these numbers, see our guide on how to analyze the Israeli property market in 2026 and our overview of market trends.
Because the investor’s purchase tax is higher than the owner-occupier’s, your effective budget is smaller than the price tag. Under a temporary order of the Israel Tax Authority, a person buying an apartment that is not their only residence pays 8% on the portion of the value up to 6,055,070 NIS and 10% on the portion above it. The order is valid until February 10, 2027, after its extension under Section 38 of Basic Law: The Knesset. The same page notes that eligible new immigrants may be entitled to significant reductions, which depend on status and must be checked against the latest guidance from the Ministry of Aliyah and Integration.
You can run your own numbers with the Tax Authority’s purchase tax calculator. The tax thresholds are updated periodically, and the Authority published an updating instruction for 2026, so check the current figures before you sign.

A simple worked example of how size interacts with this: an apartment priced at 2,000,000 NIS carries purchase tax of 8% on the full amount, which is 160,000 NIS, before a lawyer, a broker and renovation. If a 3-room unit at 1,700,000 NIS rents nearly as well as a 4-room at 2,000,000 NIS in the same area, the smaller unit saves you 300,000 NIS up front and 24,000 NIS in purchase tax. The example is arithmetic on the 8% rate, not a market quote. The question to ask is whether the 4-room’s extra rent, lower turnover and better exit justify the extra capital. Our guide to home purchase costs for buyers in Beit Shemesh lists the other items that belong in that budget.
More on yield mechanics is in our article on rental yield in Israel and on how to compare yield and growth across investment properties.
National averages hide a great deal. The CBS notes that thousands of units remain outside the effective market because of war-related damage or security concerns, which means that vacancy and rents can move quickly in specific regions as residents return or do not. The lesson for size: a 3-room apartment in one town and a 3-room apartment in another are different assets. Look at the neighborhood’s own price and rent history, the pipeline of new units nearby, and who actually lives there.
This is also why new-build and resale are different bets. A new project gives you a modern layout and a Mamad, with the risk of delivery delays and developer incentives masking the real price. A resale gives you an existing rental history and no waiting. For international buyers, especially from the US, comparing both on the same worksheet is worth the effort. Our guide for expatriates buying an apartment in Israel covers the process from abroad, and essential investment guidelines covers the strategy.
We work with families, investors and international buyers in Beit Shemesh and the surrounding areas, with a focus on new developments and on neighborhoods built for observant communities. Out of that work we hold a few firm views on size.
First, we rarely tell an investor to go as small as possible. The yield on a studio-style unit looks good on a spreadsheet, but the buyer who wants a calm, predictable asset usually does better with a 4-room apartment in a community where families want to stay. Demand in these neighborhoods is driven by schools, synagogues and daily life, not only by price.
Second, the layout matters as much as the room count. A well-planned 4-room apartment with a proper Mamad, a usable balcony and a sensible floor plan will outperform a larger, awkward one. Look at the plan before the square meters.
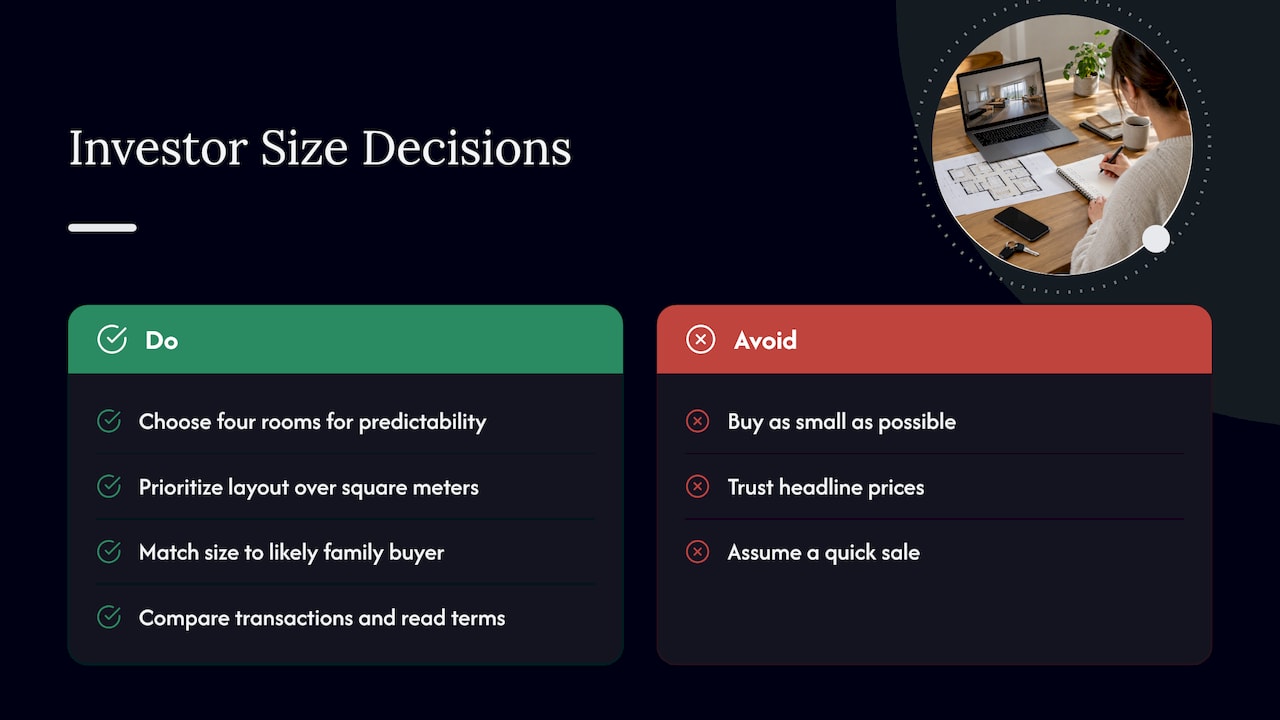
Third, ask what the exit looks like on day one. If your likely buyer is a family living in the apartment, buy the size families buy. If your plan is a short hold and a quick sale, remember the market conditions described above and keep your assumptions conservative.
Fourth, do not trust a headline price. Developer promotions and asking premiums can hide the real number, so we encourage buyers to compare actual transaction data and read the payment schedule and delivery terms line by line.
— Spiros
If you are weighing sizes in Beit Shemesh, Givat Zeev or nearby, we can walk you through what is available and how each option fits your budget and your exit plan. Our concierge project guidance covers early access to new developments, local insight and support through the purchase, including for buyers abroad. You can also browse current projects such as Neve Amim, Olmaya and Rotshtein Heights, then talk to us about which unit type suits your goals.
For most investors, a 3 or 4-room apartment with a Mamad is the safest choice, because it has the broadest pool of both tenants and buyers. Smaller units can offer a higher percentage yield but come with more turnover. Test the numbers for your exact street before deciding.
Often the percentage yield is higher because the purchase price is lower relative to the rent. The advantage can shrink once you count vacancy between tenants, repainting and a narrower resale market. Compare actual rents and prices by room count in the same neighborhood.
Yes, it can tilt the decision toward a smaller apartment that has one. The Bank of Israel found that the premium in rental asking prices rose significantly, while the premium in sale prices has fallen back from its pre-war level. Avoid paying a temporary premium, but do not buy an apartment without a Mamad if you rely on rental demand.
Under the current temporary order, 8% applies up to 6,055,070 NIS and 10% above that for an apartment that is not your sole residence, valid until February 10, 2027. New immigrants may qualify for reductions. Confirm your status and the current rates with the Tax Authority or a real estate lawyer before you commit.
Prices fell slightly in 2025 and developers hold large unsold inventories, which gives buyers more negotiating room. Transactions by investors dropped, and exits may take longer. Buy only if your numbers work with conservative assumptions, and speak to a lawyer and a mortgage adviser first.